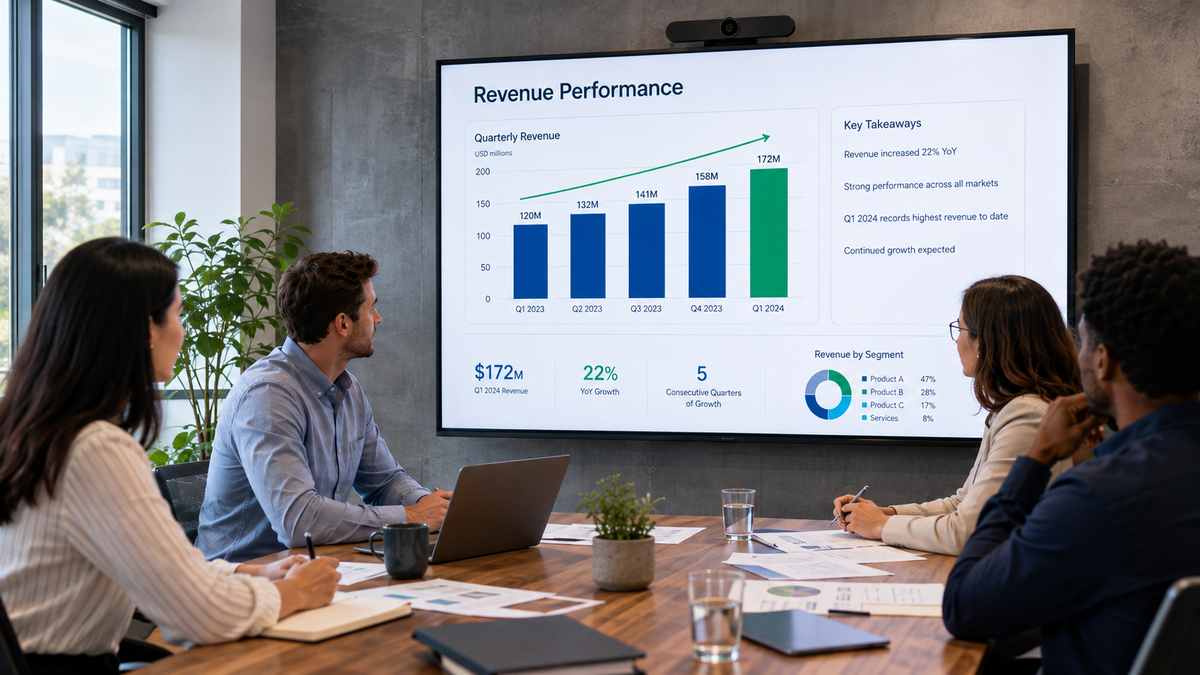
A company can be highly profitable and still worry investors, while another can lose money and see its stock rise. The difference often comes down to whether the business is still expanding and what investors believe that growth could become.
Profit gets most of the attention because it sounds like the clearest measure of success.
A company earns more than it spends, and the difference becomes profit.
But in the stock market, investors often care just as much about something that comes earlier in the income statement:
revenue.
Revenue shows how much money the business is bringing in from customers before expenses are subtracted. When that number is growing quickly, investors may see evidence that demand is expanding, the customer base is getting larger, or the company is gaining market share.
That can matter even when current profits are modest.
Revenue Shows Whether the Business Is Expanding
A profitable company is not necessarily a growing company.
Imagine a business that earns $500 million in profit every year but whose sales have been flat for several years.
Now imagine another company whose revenue is growing 30% annually, but which is spending heavily on new stores, technology, employees or manufacturing capacity.
The first company may look stronger today.
The second may look more valuable to investors if they believe those new sales will eventually produce much larger profits.
That is why revenue growth can sometimes carry more weight than current earnings.
It gives investors information about the size of the opportunity ahead.
Young Companies Often Spend Before They Earn
This is especially important for younger or rapidly expanding businesses.
A company may deliberately sacrifice current profit in order to grow faster.
It can spend heavily on:
- research and development
- advertising
- new employees
- distribution
- manufacturing
- customer acquisition
- international expansion
- new stores or facilities
Those expenses reduce profit.
But if they are also producing strong revenue growth, investors may view the spending as an investment rather than a weakness.
The central question becomes whether the company can eventually slow that spending while keeping the new customers and sales it created.
If the answer appears to be yes, a temporarily unprofitable company can still receive a very high valuation.
Profit Can Sometimes Grow for the Wrong Reason
Profit growth does not always mean the underlying business is becoming stronger.
A company can increase profit by cutting costs.
It might reduce staff, close locations, spend less on marketing, postpone investment or eliminate weaker products.
Those decisions can improve earnings in the short term.
But if revenue is also declining, investors may question how long the improvement can continue.
There is a limit to how much a business can cut.
Eventually, sustained profit growth usually requires sales growth too.
That is why analysts often look closely at whether earnings are increasing because the company is selling more or simply because it is spending less.
Investors Pay for the Future
Stock prices reflect expectations about future cash flows.
That makes growth especially important.
A company producing $1 billion in annual revenue today may be worth dramatically different amounts depending on whether investors expect that figure to become $1.1 billion or $5 billion.
Revenue growth gives investors evidence about the direction of the business.
Fast growth can suggest:
- strong customer demand
- successful products
- expanding markets
- competitive advantages
- increasing market share
None of those guarantees future profits.
But they can increase the probability that profits will become much larger later.
Different Industries Are Judged Differently
Revenue growth matters more in some industries than others.
A mature utility or consumer-products company may be expected to grow slowly while generating steady profits and dividends.
A technology company, biotechnology firm or rapidly expanding retailer may be judged much more heavily on growth.
Investors understand that businesses at different stages should not look identical.
A young software company growing revenue by 40% may be rewarded even if profits are small.
A mature company growing revenue by 2% may still be attractive if its margins and cash flow are strong.
Context matters.
Revenue Growth Is Not Enough by Itself
Strong sales growth can also be misleading.
A company could theoretically generate enormous revenue by selling products for less than they cost to produce.
That would not create a sustainable business.
Investors therefore look at several other measures alongside revenue:
- gross margins
- operating expenses
- free cash flow
- customer retention
- debt
- profit margins
- the cost required to generate each additional dollar of sales
The best growth is usually growth that becomes increasingly efficient over time.
If revenue rises quickly while losses become larger and larger, investors may eventually lose confidence.
The Combination Investors Usually Want
The strongest businesses often move through a progression.
First, revenue grows rapidly.
Then operating efficiency improves.
Eventually, more of each additional dollar of revenue becomes profit.
That transition can create enormous value.
It explains why investors sometimes tolerate low profits early in a company’s development but become much less forgiving once growth begins slowing.
A high-growth company is often being valued on what it could become.
Once that growth disappears, investors start demanding evidence of what it already is.
Growth Changes the Story
Profit answers an important question:
How much money is the company making now?
Revenue growth answers another:
How much larger could this business become?
For mature companies, current profitability may dominate the discussion.
For businesses still expanding quickly, revenue growth can reveal more about their future potential.
That is why Wall Street can sometimes celebrate a company that barely earns money while becoming concerned about another company producing billions in profit.
The numbers are telling different stories.
And in the stock market, investors are usually trying to figure out which story comes next.